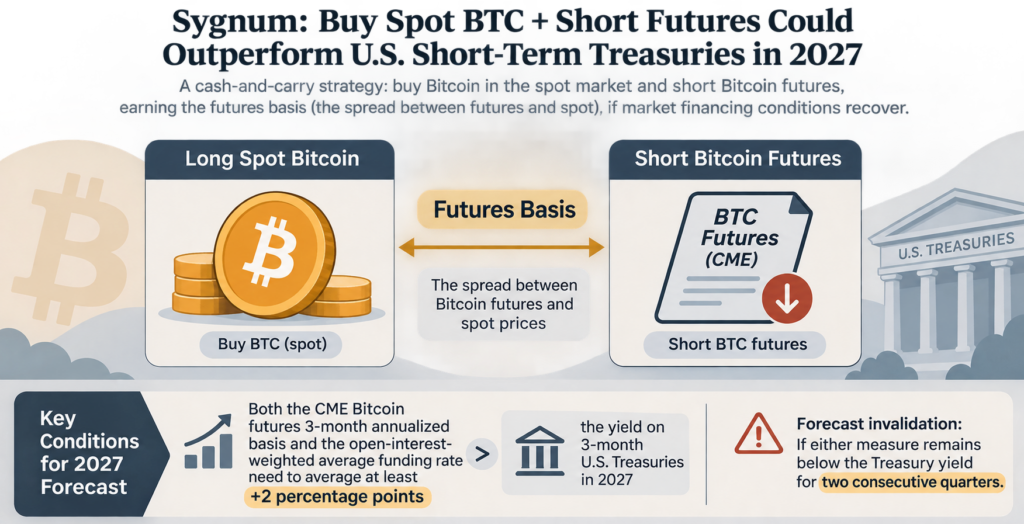
On November 19, 2026, BlockBeats reported that Swiss bank Sygnum expected a strategy of buying spot Bitcoin and shorting futures to earn an average return above short-term U.S. Treasury yields in 2027—if market financing conditions recover.
The forecast follows a weaker period in 2026. Bitcoin’s 30-day average funding rate was negative for 67 consecutive days, a stretch that ended in May. Sygnum’s report said the annualized basis on CME Bitcoin futures fell to about 3% in August, below the 3.8% yield on two-year U.S. Treasuries. By the end of October, Bitcoin funding rates had recovered to an annualized level of about 8%.
Sygnum expects wider use of digital assets and growing demand for leverage to keep funding rates and futures basis positive for much of 2027. But positive rates alone would not meet its forecast: the three-month annualized CME Bitcoin futures basis and the open-interest-weighted average funding rate would each need to average at least two percentage points above the yield on three-month U.S. Treasuries in 2027. Sygnum said it would consider the forecast invalid if either measure remained below the Treasury yield for two consecutive quarters.